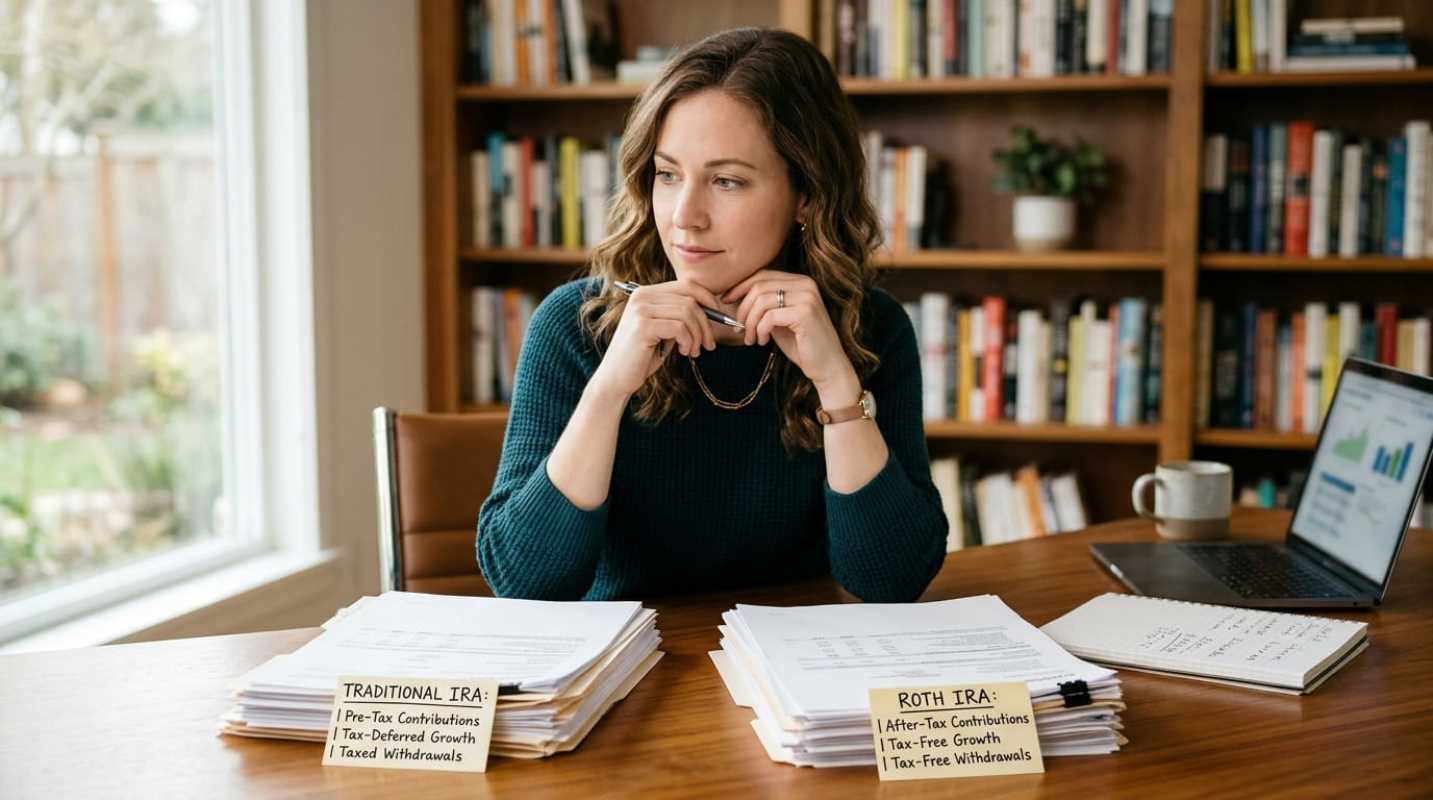
If you have ever stared at retirement paperwork and felt your eyes glaze over, you are far from alone. Deciding how to invest your hard-earned cash often comes down to one fundamental fork in the road: the Traditional IRA or the Roth IRA. Both accounts offer huge tax advantages that can speed up your journey to financial independence, but they approach the tax code from opposite directions.
The choice boils down to a simple timing question. Do you want to pay taxes now, or would you rather pay them later? Making the right move gives your savings a serious tailwind, while the wrong one could leave money on the table when you finally hang up your boots.
So what does this actually mean for your wallet, and how do you pick the account that fits your personal retirement timeline? Let's break down how both accounts work without the confusing jargon.
Traditional IRA and the Power of Tax-Deferred Growth
The Traditional IRA is built on the concept of tax deferral. When you contribute to a Traditional IRA, you often get to deduct that amount from your taxable income for the year. Put simply, if you make $75,000 and contribute $7,000, Uncle Sam treats you as if you only earned $68,000. That means an immediate reduction on your current tax bill, freeing up more cash right away.
Once your money sits inside the account, it compounds untaxed for years or even decades. You do not pay capital gains taxes when you rebalance your investments, and you do not pay taxes on annual dividend payouts. That unhindered compounding lets your portfolio snowball faster than it would in a regular taxable brokerage account.
The trade-off arrives when you retire. Every single dollar you withdraw from a Traditional IRA gets taxed at ordinary income rates, not the friendlier long-term capital gains rates. In the eyes of the IRS, those withdrawals are treated just like a regular paycheck.
Traditional IRAs also come with strings attached later in life. Under current rules, you must begin taking Required Minimum Distributions (RMDs) starting at age 73, which increases to age 75 in 2033. If you do not withdraw that mandated amount, the IRS hits you with steep penalties. These required withdrawals can push you into a higher tax bracket, increase taxes on your Social Security benefits, or trigger higher Medicare premiums.
Roth IRA and the Advantages of Tax-Free Growth
The Roth IRA flips the Traditional formula on its head. You contribute after-tax money, which means you do not get an immediate tax write-off today. You pay your regular income taxes this year, deposit the money, and let it go to work.
Here is the magic part: once your money enters a Roth IRA, you never pay taxes on it again. Decades of growth, compounding returns, and dividend payouts belong entirely to you. When you reach age 59½ and have had the account open for at least five years, every dollar you take out is 100% tax-free. Think of it like paying tax on the seed so you can harvest the entire crop tax-free.
Roth IRAs also give you unmatched flexibility compared to other retirement accounts. Because you already paid taxes on your original contributions, you can withdraw that principal amount at any time, at any age, without paying taxes or penalties. Although you should leave your investments alone to compound whenever possible, having that safety valve brings immense peace of mind.
Even better, Roth IRAs have no lifetime RMDs. If you do not need the cash to cover living expenses, you can let the account compound for your entire life and pass the balance to your heirs completely income-tax-free.
The Fine Print on Income and Contribution Limits
Before you rush to open an account, you have to verify whether you qualify. The IRS caps how much you can put into IRAs each year, and they also restrict who can use them based on income.¹
For 2026, the combined annual contribution limit across all your IRAs remains $7,000 if you are under age 50, while savers age 50 and older can stash away up to $8,000.¹ You also need taxable earned income equal to at least what you put in.
Roth IRAs carry strict income limits. If you make too much money, the IRS locks the front door
• Single filers: You can make a full Roth contribution if your modified adjusted gross income is under $150,000, with eligibility phasing out entirely at $165,000.²
• Married filing jointly: You can make a full contribution if your household income sits below $236,000, with contributions phased out completely at $246,000.²
High earners are not completely out of luck, though. Many use a legal approach known as the Backdoor Roth IRA. This involves funding a non-deductible Traditional IRA and quickly converting those funds into a Roth account, bypassing the direct income cap.
Anyone can contribute to a Traditional IRA regardless of earnings, but your ability to deduct that contribution depends on whether you or your spouse has a retirement plan at work. If your workplace offers a 401(k) and your income passes specific thresholds, your upfront tax deduction begins to shrink.²
Top Recommendations for Retirement Accounts
Balancing both accounts often yields the best results. Many long-term savers split their focus, funding a workplace plan for current tax relief while aggressively building an after-tax cushion.
Total IRA assets represent over $17 trillion in the retirement market, yet holding different tax buckets gives you the ultimate control over your future income.³ Having both accounts lets you pull money strategically during retirement, helping you stay below harsh tax brackets and Medicare surcharges.
Making the Call for Your Retirement Timeline
Choosing between these accounts comes down to comparing your tax rate today against what you expect to pay down the road. If you are in your peak earning years and paying a top-tier marginal rate, taking the deduction with a Traditional IRA makes plenty of sense. You pocket the tax savings now, assuming you will drop into a lower bracket once your working days end.
On the other hand, if you are early in your career or currently in a lower tax bracket, the Roth IRA is practically unbeatable. Paying a modest 10% or 12% tax today to secure decades of completely tax-free compounding is one of the best bargains in the entire tax code.
Here is a quick checklist to help guide your decision
• Go with a Traditional IRA: Choose this path if you are in a high tax bracket today, expect your income to fall significantly in retirement, and need an immediate tax deduction to lower your current bill.
• Go with a Roth IRA: Pick this option if you are in a lower or moderate bracket, have decades of compounding ahead of you, want the freedom to pull contributions penalty-free, or want to avoid forced minimum distributions later in life.
If you still feel torn, remember that you do not have to pick just one. You can split your contributions between both account types in the same tax year, so long as your total deposits do not exceed the annual IRS limit. Start putting your money to work today, and let the math do the heavy lifting for your future.
Sources:
1. Retirement topics - IRA contribution limits
https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-ira-contribution-limits
2. IRA contribution limits and eligibility
https://www.ameriprise.com/products/investments/iras-retirement-plans/ira-contribution-limits-eligibility
3. IRA ownership climbs as rollovers drive retirement savings growth
https://www.investmentnews.com/retirement-planning/ira-ownership-climbs-as-rollovers-drive-retirement-savings-growth-ici-finds/266864
*This article on AimText is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match .jpg)