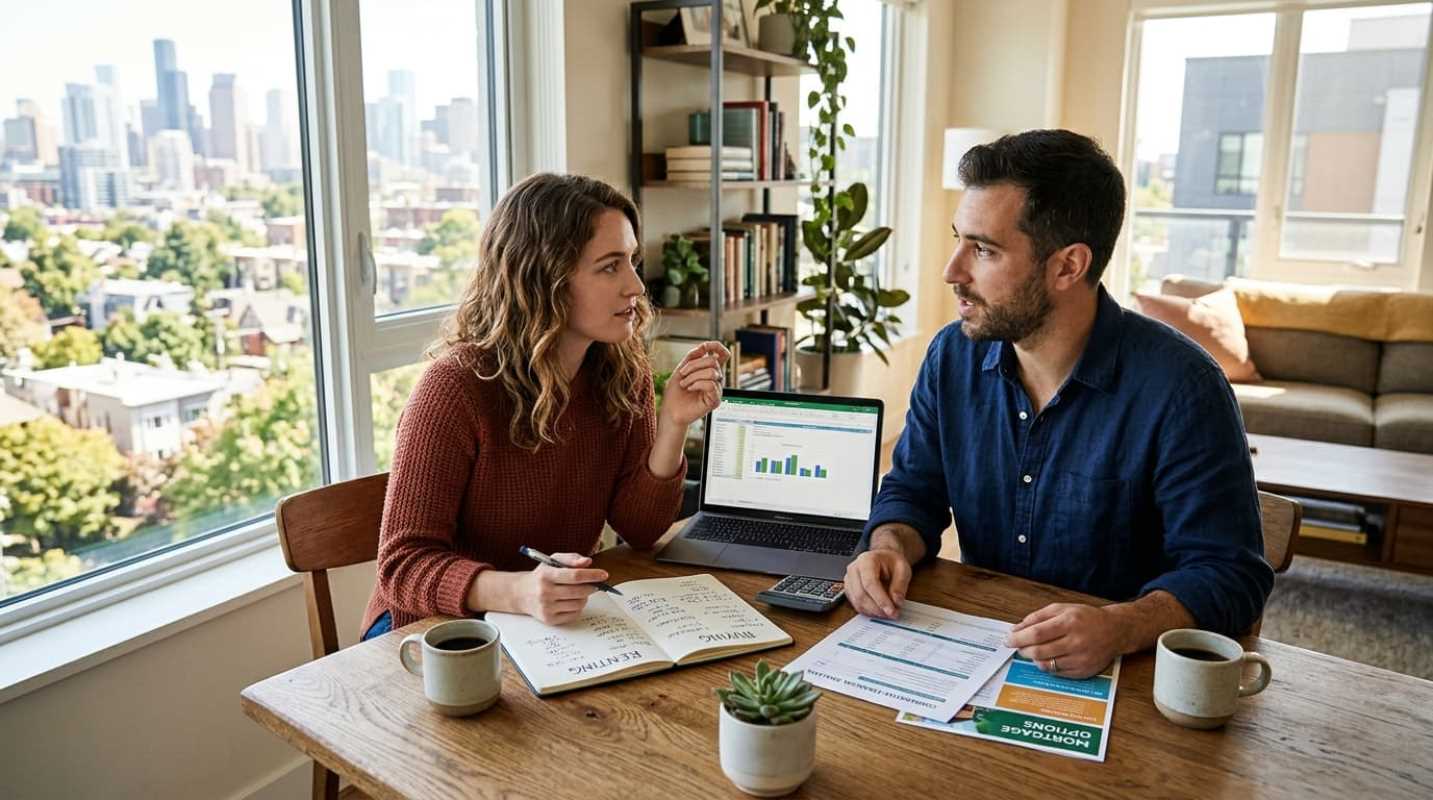
Have you ever heard an older relative declare that renting is just throwing your hard-earned money down the drain? It's one of the most stubborn pieces of financial advice in modern culture. For decades, the script was simple: graduate, get a job, buy a home, and build your wealth. But in 2026, sticking blindly to that old playbook could cost you hundreds of thousands of dollars.
The housing market has shifted dramatically over the past few years. Between elevated mortgage rates and sky-high home prices, the gap between the cost of owning and renting is wider than it's been in a generation. Deciding whether to sign a lease or take on a 30-year mortgage requires running the actual numbers, not relying on outdated rules of thumb.
The Myth of 'Renting is Throwing Money Away'
Let's dismantle this cliché right away. When you buy groceries, do you complain that you threw your money away because you don't have any money left over at the end of the month? Of course not. You paid for sustenance.
Rent works the same way. You're purchasing a basic human need: shelter. You're paying for a roof over your head, functioning heat, running water, and a safe place to sleep. That's a service, not a scam.
Renting also gives you something homeownership often steals: lifestyle mobility. If you land a dream job across the country or want to downsize next year, you just wait for your lease to end. When you own, moving involves months of preparation, contractor repairs, and massive transaction bills.
The math has also changed in favor of tenants. Recent data from Redfin shows that the average American household needs around $111,000 in annual income to afford a median-priced home, compared to roughly $76,000 to rent a comparable place.¹ That's a staggering $35,000 income gap just to get through the front door of ownership.
Calculating the Total Cost of Ownership
The biggest financial mistake prospective buyers make is comparing their monthly rent check directly to a mortgage principal and interest payment.
Have you ever looked at a home listing and thought, "My rent is $1,900, and this mortgage is only $2,100, so buying is barely more expensive"? That assumption is dangerous. Principal and interest are just the starting line.
When you buy a home, you take on non-mortgage holding costs that quietly drain your bank account
• Property taxes: These can easily run from $4,000 to $10,000 or more each year, depending on your state and county.
• Homeowners insurance: Insurance premiums have spiked across the country, especially in regions hit by frequent severe weather.
• HOA dues: Homeowners association fees can add hundreds of dollars each month without building a dime of equity.
• Maintenance and repairs: You need to budget 1% to 2% of your home's total value every single year for routine upkeep and replacements. On a $400,000 property, that's $4,000 to $8,000 per year just to keep the roof intact and the pipes working.
Studies tracking the hidden expenses of homeownership found that these non-mortgage costs climbed to an average of over $18,000 annually.²
Think of it like this: your monthly rent is the maximum amount you will pay for housing that month. Your monthly mortgage payment is the absolute minimum you will pay.
Finding Your Break-Even Point
Does this mean buying a home is always a bad move? Not at all. It just means you need time on your side.
The break-even point is the exact moment when the financial gains of owning (equity paydown, tax deductions, and property appreciation) overcome the upfront costs of buying (closing fees, loan origination, inspections) and the ongoing unrecoverable expenses.
Recent market data from Realtor.com shows national rents hovering between $1,670 and $1,950 while home values remain near all-time highs.³ Because of that spread, the national average break-even point sits at roughly six years.
If you live in an affordable inland market, your break-even horizon might only be three to four years. But if you're in a high-cost coastal metro like Seattle, Los Angeles, or Austin, your break-even timeline can easily stretch past ten or fifteen years. In some expensive tech hubs, buying may never mathematically beat renting and investing the difference.
To gauge your local market, calculate the price-to-rent ratio by dividing the median home purchase price by the annual rent for an equivalent home
• Ratio under 15: Buying has a clear edge, and you'll likely break even quickly.
• Ratio between 16 and 20: The numbers are close, so your personal timeline decides the winner.
• Ratio above 21: Renting is vastly cheaper every month, putting the financial advantage on the renter's side.
The Opportunity Cost of Your Down Payment
Where you park your cash matters just as much as what you spend each month.
Putting down 20% on a $400,000 house requires $80,000 in cold, hard cash, plus another $10,000 to $15,000 in closing costs. The moment you hand that money over at closing, it's locked into drywall and dirt.
What happens if you invest that cash in a low-cost stock index fund instead?
Historically, the stock market has delivered long-term annualized returns between 8% and 10%, while residential real estate values have closely tracked general inflation over multi-decade periods. When you lock up all your savings in home equity, you miss out on that compounding market growth.
There's also the monthly savings gap. In most major cities, renting saves you several hundred dollars every month compared to the full cost of owning that same home. If you take that monthly savings and consistently funnel it into an investment portfolio, you can build serious wealth without ever touching a lawnmower or replacing a broken water heater.
Liquidity is safety. You can't sell three bricks from your living room wall to cover an unexpected medical bill. Having liquid investments gives you options that home equity simply cannot match.
Before you make a final move, use specialized tools to model your local market numbers and compare your long-term wealth trajectories.
Making the Decision Through a Strategic Framework
How do you make the right call for your own life? Run your decision through this practical checklist
• Your expected timeline: If you can't guarantee you'll stay in the same home for at least five to seven years, stick with renting. Selling too soon will almost certainly cost you money after paying 5% to 8% in agent commissions and transfer taxes.
• Your cash cushion: If buying a house drains your bank account to zero, don't do it. You need a 20% down payment, several thousand dollars for closing fees, and a separate emergency fund with three to six months of expenses. Becoming "house-poor" is a fast track to financial stress.
• Your willingness to invest: Renting only builds wealth if you actually invest the money you save on monthly payments and down payment cash. If you spend the difference on vacations and dining out, forced home savings through a mortgage will win every time.
• Your lifestyle goals: If you love painting walls, building gardens, and putting down permanent roots in a neighborhood, buying offers psychological value that money can't track. If you value freedom, career flexibility, and minimal chores, renting is an incredible tool.
Align your housing choice with your actual life plans, not social expectations. Run the numbers honestly, protect your savings, and choose the path that grows your net worth on your own terms.
Sources:
1. Redfin Rent Versus Buy Analysis
https://www.redfin.com/news/rent-versus-buy-2026/
2. The Hidden Costs of Homeownership
https://www.ownwell.com/insight/hidden-costs-of-homeownership-silent-inflation
3. Realtor.com Rental Market Trends
https://www.realtor.com/research/march-2026-rent/
*This article on AimText is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match .jpg)
