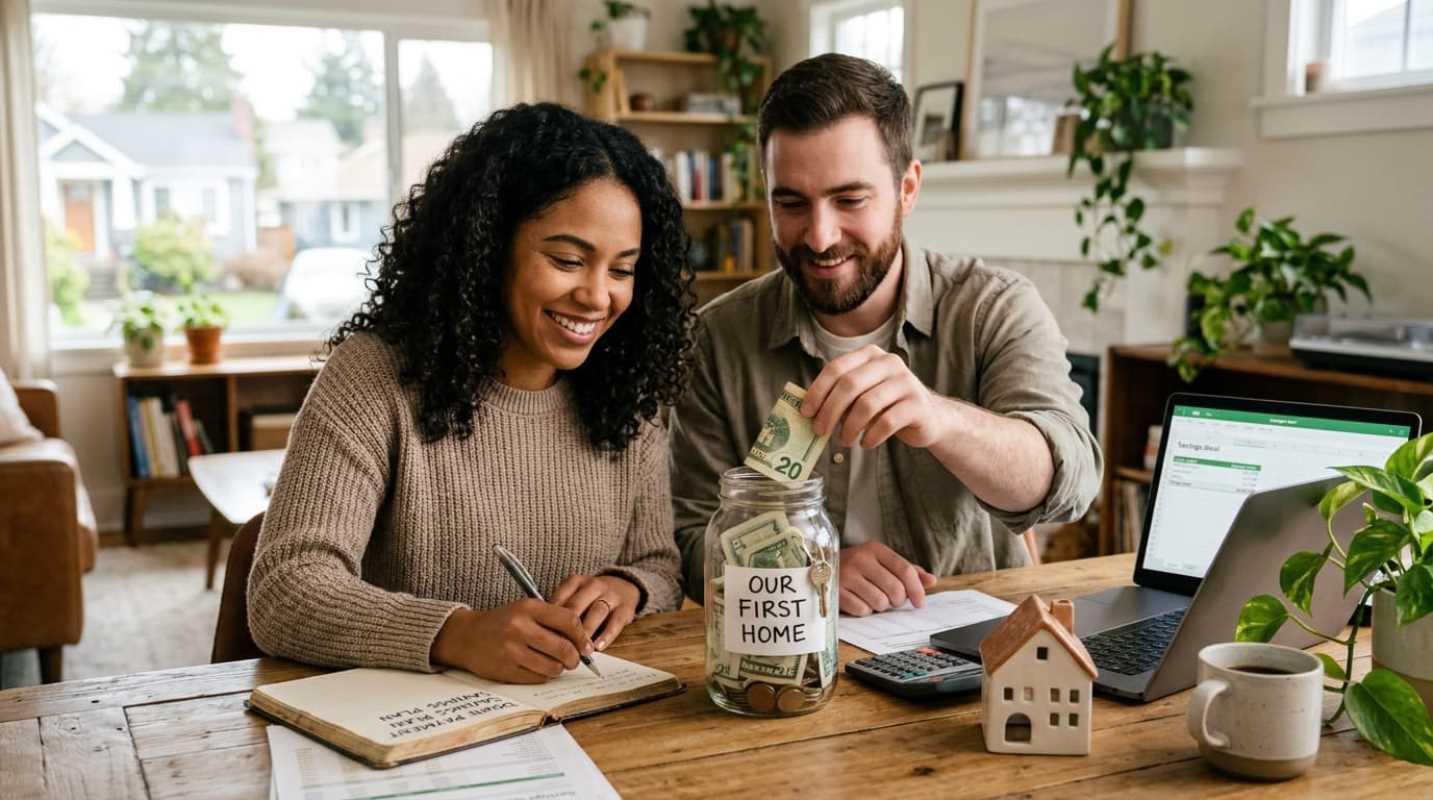
Buying your first home can feel like trying to hit a moving target. With home prices sitting near record highs, the idea of scraping together tens of thousands of dollars might seem completely out of reach. Have you looked at home listings online, done some quick math on a down payment, and immediately closed the tab in frustration? You aren't alone.
Saving that initial pile of cash is often the single hardest step in the entire homebuying journey. High rent, car payments, and everyday living costs make it tough to put money aside. But buying your first place does not require you to live on instant noodles for five years or hand over a massive 20% check on closing day. With a clear target, a streamlined budget, and the right tools, you can build your fund faster than you think.
The Reality Check and Setting Your Savings Goal
The biggest hurdle for most first-time buyers is a simple misunderstanding about how much cash they actually need. You have probably heard family members or friends insist that you must put 20% down. That rule is completely outdated.
According to data from the National Association of Realtors, first-time buyers recently dropped to just 24% of all home purchases, and their median age climbed to 38 years old.¹ That shift happened partly because people assume they need an unattainable sum before they can even speak to a lender. The truth? First-time buyers actually put down a median of only 9% to 10%.²
On a $400,000 starter home, a 10% down payment is $40,000. That is half of the mythical $80,000 figure people quote. Better yet, many programs allow you to buy with far less
• Conventional 97 and Fannie Mae HomeReady: allow down payments as low as 3% for qualified buyers.
• Federal Housing Administration (FHA) loans: require just 3.5% down with a credit score of 580 or higher.
• VA and USDA loans: provide 0% down financing for eligible military service members and rural property buyers.
What does this mean for your bank account? On that same $400,000 home, a 3.5% down payment comes out to $14,000. You will also need to cover closing costs, which generally run between 2% and 5% of the loan amount. Add those numbers together, and you have your true finish line. Once you know your target number based on your local market, divide it by the number of months you want to spend saving. A $20,000 goal over two years breaks down to roughly $833 a month. That gives you a realistic benchmark you can actually track.
Audit Your Finances and Cut the Fluff
Once your target number is locked in, you need to look at your cash flow with clear eyes. Where is your money leaking each month?
Start by printing out your bank and credit card statements from the last ninety days. Highlight recurring charges you forgot about, like streaming platforms you barely open, premium gym subscriptions, or meal delivery convenience fees. Trimming those subscriptions won't buy you a house by itself, but it instantly frees up cash that can go directly toward your down payment.
Next, look at your existing debt. If you are carrying credit card balances with a 22% interest rate, aggressive house saving can wait. Paying high interest drains your cash reserves every month. Knock out toxic, high-interest balances first. will this free up monthly income for your down payment later, but it also improves your debt-to-income ratio, which lenders inspect when you apply for a mortgage.
Finally, set up a dedicated account for this project. Never leave your down payment stash sitting in your primary checking account. If the money is mixed in with your grocery and utility cash, you will spend it. Move it to a separate, dedicated account and treat it as locked away.
Make Saving Effortless with Automation
Willpower is an unreliable financial approach. If you wait until the end of the month to save whatever cash is left over, you will usually find that nothing is left.
The most reliable approach is to pay yourself first. The moment your paycheck clears, your savings transfer should happen immediately. Think of it like a mandatory bill that you owe to your future self.
An easy way to handle this is payroll direct deposit splitting. Ask your employer's HR or payroll department to split your pay across two accounts. You can direct 15% straight into an isolated savings account, while the remaining 85% goes into your standard checking account for living expenses. Because that savings portion never hits your everyday balance, you won't be tempted to spend it.
Where should that cash sit? Keep it in a high-yield savings account (HYSA). Traditional banks often pay a measly 0.01% interest. A good high-yield account pays between 4% and 5% in annual interest, backed by FDIC insurance. On a $25,000 balance, a 4.5% rate generates over $1,100 in free, compounded interest in a single year.
To boost your momentum, use micro-saving tools that round up your everyday debit card purchases to the nearest dollar and stash the difference. It is the digital equivalent of dropping spare pocket change into a glass jar. You will hardly notice thirty cents here and seventy cents there, but it can quietly add hundreds of dollars to your fund every year.
Finding Support Through First-Time Buyer Programs
You do not have to build your entire down payment alone. Thousands of buyers get across the finish line every year by taking advantage of specialized buyer assistance.
According to Down Payment Resource, over 2,500 homebuyer assistance programs are operating nationwide.³ Every single county in the country has access to at least one of these programs. Even better, roughly 80% of these programs offer deferred payments, and more than half provide forgivable second mortgages. If you stay in your home for a specified period (usually five to ten years) without refinancing or selling, that assistance loan is completely forgiven.
Many buyers assume they make too much money to qualify for assistance, but income limits have expanded significantly. Most programs feature income caps well above $100,000, and some have no income limits at all.
Major commercial banks also offer proprietary grant programs that provide $5,000 to $10,000 toward down payments or closing costs in select areas, money that never has to be paid back. Before you resign yourself to years of slow saving, search your state housing finance agency website to see what local grants and low-interest down payment loans you qualify for today.
Boosting Your Income Without Burning Out
Cutting back on spending helps, but your savings rate has a hard ceiling: you can only cut your expenses to zero. Increasing your income, on the other hand, has unlimited upside.
If you want to accelerate your timeline, consider taking on a targeted side gig where 100% of the earnings go straight into your house fund. You might tutor students online, pick up freelance design projects, or do weekend rideshare driving. The key is to assign that income a specific job. When you know every extra hour worked brings you closer to your own front door, the extra effort feels purposeful.
You can also accelerate your timeline by capturing windfalls
• Tax refunds: route your annual IRS refund straight into your high-yield savings account instead of spending it on vacations.
• Work bonuses and raises: keep living on your baseline salary and send every dollar of an annual performance bonus directly to your down payment.
• Cash gifts: if family members offer financial gifts for birthdays or holidays, ask them to contribute directly to your home fund.
Saving for a house is a marathon, not a sprint. Do not strip all the joy out of your life to hit your goal six months faster. Build a plan that leaves room for dinner with friends, stick to your automated system, and trust the process. Step by step, that down payment fund will turn into the keys to your first home.
Sources:
1. First-Time Home Buyers Shrink to Historic Low of 24% as Buyer Age Hits Record High
https://www.nar.realtor/press-releases/first-time-home-buyers-shrink-to-historic-low-of-24-as-buyer-age-hits-record-high
2. Down Payment Statistics
https://www.paperlesspipeline.com/blog/down-payment-statistics
3. 2025 Kicks Off With Record Number of Homebuyer Assistance Programs
https://downpaymentresource.com/professional-resource/2025-kicks-off-with-record-number-of-homebuyer-assistance-programs/
*This article on AimText is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match .jpg)
