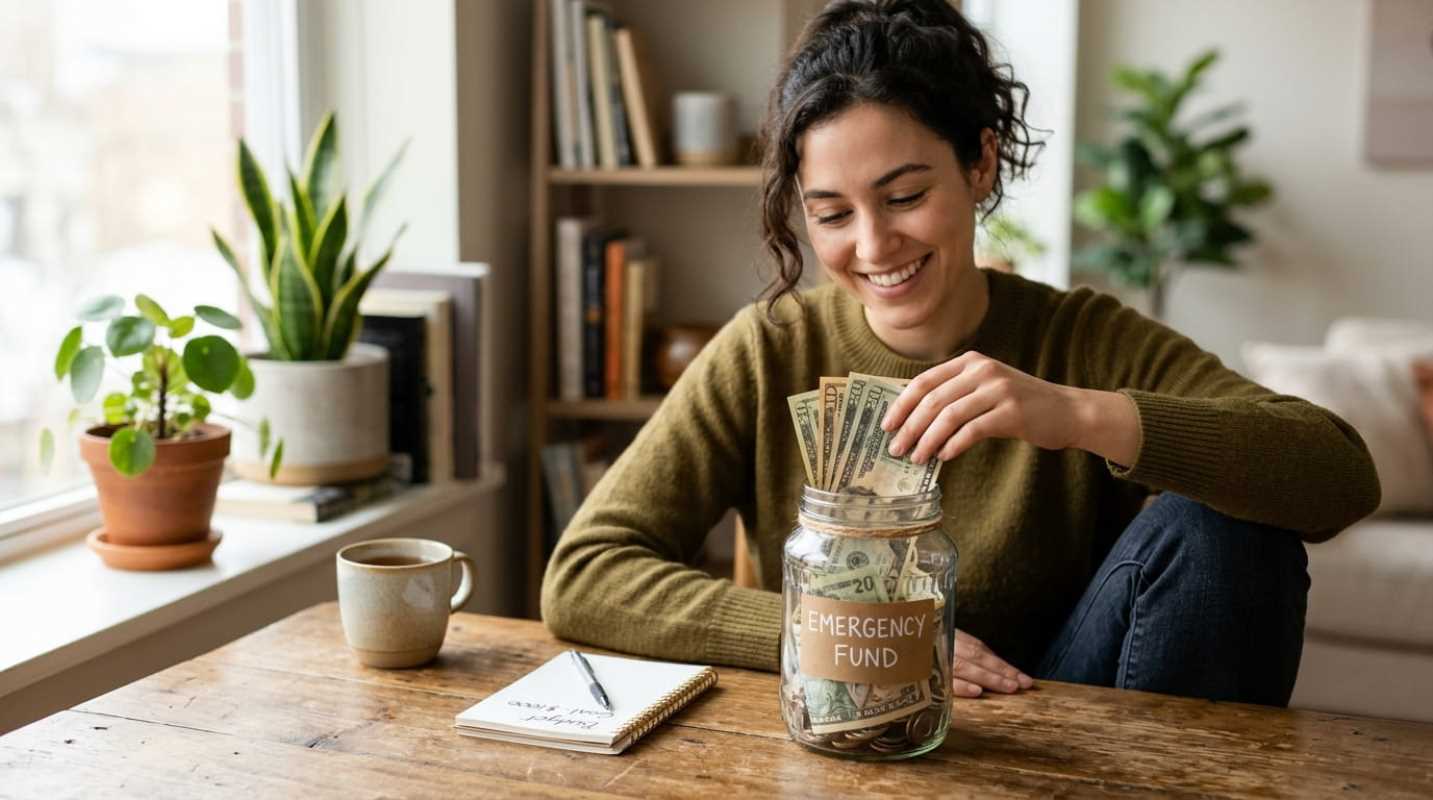
You know the sinking feeling. Your tire blows out on the highway, your water heater floods the basement, or you get an unexpected medical bill in the mail. If your immediate reaction is panic, followed by reaching for a credit card, you are far from alone. Life has a way of throwing curveballs when you least expect them. Building a dedicated stash of cash from zero might feel impossible when bills take up most of your paycheck, but it is one of the most practical things you can do for your sanity.
Here is how you can build a reliable emergency fund from scratch, one practical step at a time.
Why You Need a Financial Safety Net Today
An emergency fund buys breathing room. When an unexpected expense hits, cash in the bank turns what could be a life-altering crisis into a temporary inconvenience.
The reality check is simple: unexpected expenses are guaranteed to happen. According to Bankrate's annual savings studies, only 41% to 44% of adults in the United States could cover a surprise $1,000 expense from their savings.¹ Around a quarter of Americans have zero cash cushion at all.
When you do not have cash ready, life forces you to borrow. Relying on credit cards with interest rates north of 20% turns a $500 car repair into an ongoing financial drain. You pay interest on top of interest, month after month, digging yourself into a deeper hole. Breaking that cycle starts with putting a cash barrier between your daily life and the unexpected.
Starting Small and the Power of Micro Savings
The biggest obstacle to building an emergency fund is usually the target number itself. When personal finance guides tell you to save $15,000, it is easy to throw your hands up and quit before you begin.
Forget about five-figure sums for now. Your immediate focus is getting your hands on your first $500.
Finding $500 does not require a dramatic lifestyle overhaul. It comes from tiny, intentional choices
• Run a 30-day subscription audit: Check your bank statements for recurring charges you forgot about. Streaming platforms, unused gym memberships, and app subscriptions often add up to $40 or $60 a month.
• Sell unused household items: Walk through your closet, garage, or attic. Listing an old phone, unused sports gear, or furniture online can quickly produce a few hundred dollars.
• Pick up one short-term gig: Delivering groceries, dog walking, or freelancing for a single weekend can easily fund your starter cash cushion.
• Use the 50/50 windfall rule: Whenever you get a tax refund, birthday cash, or a work bonus, put half toward your starter fund and use the other half for daily expenses or treats.
Starting small always beats waiting for the perfect financial moment. Five dollars saved this week is better than an ambitious plan you never start.
Setting Realistic Savings Milestones
Once you build momentum, you need a roadmap. Modern financial planners recommend hitting milestones in phases rather than chasing an all-or-nothing goal.
1. Phase 1: The $1,000 Starter Buffer. This gives you an immediate firewall against minor hiccups, such as an urgent care copay or an unexpected car battery replacement. If you have credit card debt, hold here and make minimum payments while keeping this buffer intact.
2. Phase 2: The One-Month Survival Budget. Calculate what you need just to get through 30 days. This means your bare-bones expenses: rent or mortgage, basic groceries, utilities, transportation, and minimum debt payments. Dining out and entertainment do not count.
3. Phase 3: The Three to Six Month Cushion. Once your high-interest debt is under control, expand your fund to cover three to six months of basic living costs. Federal Reserve data shows that about 54% of American adults maintain a three-month cushion.² If you have a stable job and a dual-income household, three months may be plenty.
4. Phase 4: Extended Security. If you are a freelancer, work on commission, or run a single-income household with kids, consider expanding your reserve to nine or twelve months of expenses.
Every milestone you hit brings an incredible psychological boost. Celebrate the $1,000 mark. Celebrate the one-month mark. Each tier gives you more independence.
Automating Your Way to Success
Relying on willpower to save money rarely works. If you tell yourself you will save whatever is left over at the end of the month, you will usually find that nothing is left.
The fix is simple: remove yourself from the equation. Set up an automatic transfer through your bank so money moves to savings the morning your paycheck arrives. Even better, ask your employer's payroll department to split your direct deposit into two accounts. When the money never touches your checking account, you never miss it.
Where you park this cash matters just as much. Leaving your safety net in an everyday checking account tempts you to spend it. Putting it into a traditional brick-and-mortar savings account is not much better, since those often pay as little as 0.05% APY.
Instead, park your fund in an online High-Yield Savings Account (HYSA). Top-rated high-yield accounts offer interest rates well above 3.50% or 4.00% APY without locking your money away.³
• Higher growth: A $5,000 balance in a traditional savings account earns a couple of dollars a year. In an HYSA, that same cash generates over $200 in annual interest.
• Zero market risk: Unlike stocks or mutual funds, money in an HYSA is safe and insured up to $250,000 by the FDIC.
• Healthy friction: Keeping your funds at an online bank separate from your primary checking account creates a one- to two-day transfer delay. That brief window is often enough to stop you from spending money on impulse purchases.
Having the right banking tools makes separating everyday cash from your reserve simple. Look for accounts that let you organize your savings into separate digital envelopes or buckets for specific emergencies.
Maintaining and Protecting Your Fund
Building an emergency fund is only half the battle. You also have to protect it from yourself.
Before tapping into your reserve, run the expense through a quick three-part filter
• Is it unexpected?: A holiday gift or your annual car insurance premium is not an emergency. Those are predictable events that belong in separate sinking funds.
• Is it necessary?: You must separate true needs from convenient wants. A broken refrigerator is a necessity. A newer television because the old one looks small is not.
• Is it urgent?: Does this need to be fixed in the next 24 to 48 hours to prevent financial harm, health risks, or job loss?
When a genuine emergency happens, do not feel guilty about using your money. That is why you saved it in the first place. Once the crisis passes, treat your fund like an active bill. Pause any extra discretionary spending and redirect your cash flow toward replenishing the account back to your target balance.
Think of your emergency fund as a permanent part of your life. It is not a short-term chore you finish and forget. It is your financial shock absorber, protecting your future whenever life gets bumpy.
Sources:
1. Bankrate Emergency Savings Report
https://www.bankrate.com/banking/savings/emergency-savings-report/
2. Federal Reserve Survey of Household Economics and Decisionmaking
https://www.federalreserve.gov/consumerscommunities/sheddataviz/emergency-savings-table.html
3. CNBC Select Best High-Yield Savings Accounts
https://www.cnbc.com/select/best-high-yield-savings-accounts/
*This article on AimText is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match .jpg)