Starting a new venture brings an endless checklist. You need to build your product, build a website, find clients, and figure out how to get paid. Somewhere near the top of that list sits a question that trips up thousands of founders: What legal structure should you pick?
The choice you make right now affects your daily legal risk, your paperwork load, and how much money you hand over to the IRS each April. Pick the wrong one early on, and you could leave your personal savings exposed to lawsuits. Wait too long to change it, and you might overpay on taxes by thousands of dollars every year.
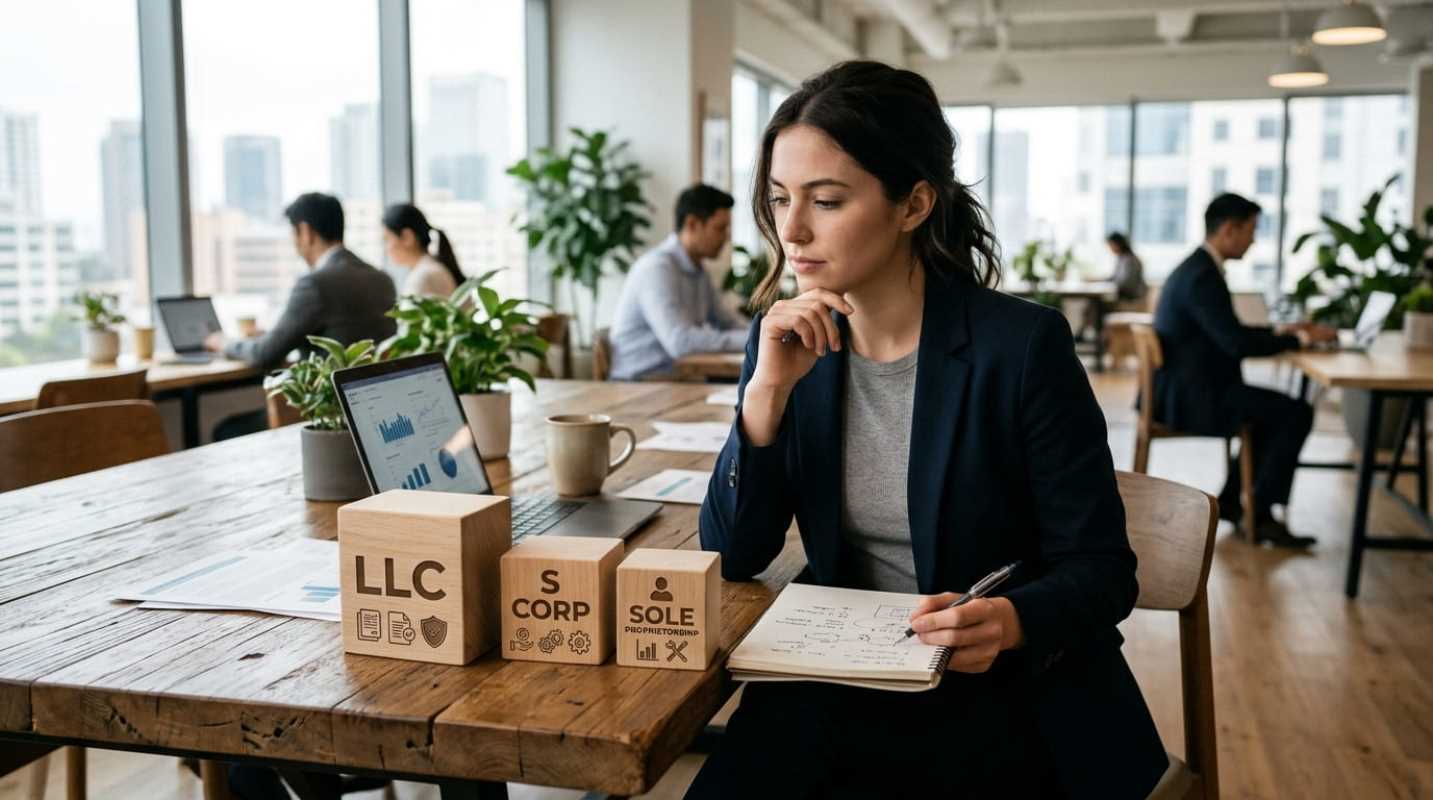
So what does this actually mean for your day-to-day operations? Let us break down the sole proprietorship, the limited liability company (LLC), and the S Corporation election so you can set up your business with total clarity.
The Sole Proprietorship and Simplicity Over Security
If you start selling consulting services, baking cakes, or doing freelance design without filing state paperwork, you are automatically a sole proprietor. It is the default setting for doing business in America. There are no state filing fees, no formal articles of organization, and no separate corporate tax returns.
That simplicity is tempting, but it comes with a massive blind spot: unlimited personal liability.
In a sole proprietorship, you and your business are legally the same person. If a client slips on your studio floor, sues you for breach of contract, or your business defaults on debt, creditors can go after your personal assets. That includes your personal checking account, your vehicle, and even the equity in your home.
Commercial insurance policies help, but insurance policies have claim exclusions, coverage caps, and legal fights. Relying solely on an insurance policy without a legal liability shield is like driving without a seatbelt just because your car has an airbag. For simple weekend side gigs with zero financial risk, a sole proprietorship is fine. Once you take on commercial clients, sign contracts, or hire help, that lack of protection becomes a real danger.
The LLC as the Flexible Standard for Small Business
A limited liability company provides a statutory shield between your company and your personal life. When you register an LLC with your state, you establish a separate legal entity. The business owns its assets, signs its own contracts, and takes on its own debts.
If disaster strikes and your LLC faces a judgment, the creditor can generally only seize the assets owned by the LLC. Your personal house, retirement accounts, and family savings stay behind a protective legal barrier known as the corporate veil.
To keep that shield intact, you have to treat the LLC like an independent entity
• Separate your finances: You must open a dedicated business bank account and never mix personal and company money.
• Draft an operating agreement: Even for a single-member LLC, this internal document proves you run a formal company.
• Maintain state filings: You need to keep up with your state annual reports and franchise fees to stay in good standing.
From a tax perspective, the IRS treats a single-member LLC as a pass-through entity by default. You do not file a separate corporate tax return. All your business profits flow straight to your personal Form 1040 on Schedule C. You get corporate-style liability protection without the suffocating red tape of a traditional corporation.
The S Corp Election for Strategic Tax Planning
Here is one of the most common points of confusion: an S Corporation is not a distinct state entity type. You cannot walk into your secretary of state office and form an S Corp. Instead, it is a federal tax status created by filing Form 2553 with the IRS.³
Why would you elect S Corp status? In a standard LLC or sole proprietorship, you pay self-employment taxes (15.3% for Social Security and Medicare) on 100% of your net profits up to the statutory caps. When your net income grows, that self-employment tax bill gets painful fast.
An S Corp election lets you divide your net earnings into two separate buckets
• W-2 salary: You pay yourself a regular employee paycheck, which is subject to standard payroll taxes.
• Shareholder distributions: You take the remaining profit as a distribution, which is completely free from self-employment tax.
There is a catch, and the IRS watches it closely. You cannot pay yourself a $10,000 salary on $150,000 of profit just to escape payroll taxes. The IRS requires you to pay yourself a reasonable salary based on what an independent company would pay someone for your role in your local market.³ If you cut corners here, the tax authorities can reclassify your distributions as wages and hit you with heavy back taxes and penalties.
Comparing Tax Implications and Administrative Burdens
Choosing the right structure comes down to balancing administrative overhead against potential tax savings
• Sole Proprietorship: Offers zero liability protection, requires Schedule C tax filing, subjects 100% of net profits to self-employment tax, and costs almost nothing to maintain.
• Default LLC: Gives you strong liability protection, uses simple pass-through taxation, still subjects 100% of profit to self-employment tax, and requires modest state fees ranging from $50 to $800 annually.
• LLC with S Corp Election: Inherits the strong liability shield of the LLC, limits payroll taxes to your W-2 wages only, but requires $1,500 to $4,000 in baseline annual overhead for payroll software and Form 1120-S corporate tax preparation.⁴
Remember that Social Security taxes apply up to a specific wage base each year, such as the $176,100 threshold in recent federal guidelines.⁶ Beyond payroll taxes, you must also consider the Section 199A Qualified Business Income (QBI) deduction. In a standard LLC, the 20% QBI deduction applies against your entire net profit. In an S Corp, your W-2 wages are excluded from QBI, which reduces the size of your deduction.
When does switching to an S Corp pay off? As a rule of thumb, most small businesses need consistent net profits above $70,000 to $100,000 per year before the payroll tax savings outweigh the added accounting and compliance bills.⁴
Consider a business generating $120,000 in net profit. As a default LLC, you pay roughly $16,955 in self-employment taxes on that income. With an S Corp election, you might pay yourself a reasonable salary of $60,000 and take the remaining $60,000 as a distribution. Your payroll taxes drop to around $9,180. Even after paying an extra $2,500 for payroll processing and corporate tax filings, you still walk away with $4,500 to $5,500 in clean annual savings.⁴
Making Your Final Move with Confidence
Do not let analysis paralysis stall your business launch. If you are testing a low-risk idea on the weekends, start as a sole proprietor to validate your concept. Keep overhead at zero and focus on getting your first paying clients.
The moment you sign real contracts, take on debt, or earn steady revenue, form an LLC. It gives you the personal asset protection you need without drowning you in administrative busywork.
Once your business gains traction and your net profit consistently crosses that $80,000 mark, schedule a meeting with a qualified CPA. They can run a compensation study, verify whether the S Corp tax savings make sense for your situation, and help you file Form 2553 at the right time. Taking it step by step keeps your overhead low when you start and shields your wealth as you grow.
Sources:
1. AE Tax Advisors
https://www.aetaxadvisors.com/blog/when-should-i-switch-from-llc-to-s-corp/
2. Caro & Associates
https://caroandassociates.com/learning-center/posts/s-corp-vs-llc-when-the-switch-actually-pays/
3. Landmark CPAs
https://www.landmarkcpas.com/social-security-wage-base/
*This article on AimText is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*